Table tennis betting tips for the 2026 calendar
 Available in US
Data current as of 27 October 2026 and checked against the Gambling Commission’s public register of remote operating licences. Table tennis sits in an odd place in British betting. The ITTF World Tour, the WTT series and the European championships fill the in-play feed almost every week of the year, yet a price on a fifth set between two ranked opponents from Mongolia or Romania still feels niche to a punter raised on football and horse racing. That gap between the volume of fixtures on offer and the familiarity of the market is the gap this guide closes — what a price is telling you, what the margin hides, how an in-play rally reads when the server has changed, and which of the ten licensed brands below earn a place in a punter’s rotation.
This is a guide, not a tip sheet. No pick, score or selection on this page is a prediction, because nobody can predict a match and a reader who acts on one loses money on the page’s word. What follows is the machinery: how a value bet is built from form, statistics and the bookmaker’s own odds; what a margin of five per cent means for a stake on the favourite; what a free bet really pays back once the qualifying wager is counted; and what responsible gambling tools the licence gives a punter who wants them. Read it as one long briefing, and the operators below as a starting shortlist — ten of the licensed brands, named and judged for what each does well, not recommended as the one to bet with.
Markets and odds: the bedrock of a price
What a table tennis match actually looks like
A game goes to the first player to eleven points, with a two-point margin once both players reach ten — so a deuce at 10–10 is decided by the next lead of two rather than by any sudden-death rule. Service changes every two points throughout the regular game; once ten-all is reached the serve alternates after every point. Matches are best of an odd number of games, with five and seven the usual competition formats. Those three rules — eleven points, two-point margin, alternating serve — shape every market on the slate. A handicap of minus 1.5 games means the player must win by two clear games, a margin that maps directly onto the two-game lead required in the scoreboard; an over/under 18.5 total games is a wager on whether a match stretches to a deciding set.
The dimensions matter for handicap reading too, even though the punter never sees the table. The playing surface is 2.74 m long, 1.525 m wide and 76 cm high with the net 15.25 cm above it; the ball is 40 mm across and 2.7 g. None of that figures in a price, but it explains why a player with a long reach and an aggressive short game can dominate from the backhand corner and why a tall defender with a strong lob is worth comparing against a low, flat hitter on slower surfaces. The reader who understands the geometry reads the player profiles more sharply than the reader who treats a name as a number.
From match winner to total games: how the bookmaker divides the action
A bookmaker’s table tennis coupon is built in layers. The base layer is the match winner — Player A, Player B, sometimes a third option for the draw at 1–1 sets after two played (in best-of-five formats where a dead rubber is possible). On top of that come totals: over/under a number of total games, over/under a number of total points in a single game, and a handicap line on games. Then the in-game markets once a match is underway — who wins the next game, who wins the race to a target score, whether the score goes to deuce. And finally the combination products: a bet builder that joins a per-match handicap to a total-points line on the same match into a single price.
Each of those layers carries its own margin. The match winner market on a balanced match typically holds a bookmaker’s edge of four to six per cent; the totals and handicaps sit slightly higher because the pricing models are less refined and the liquidity is thinner; a bet builder carries a margin stacked on top of the margin of each leg, which is why a four-leg builder on a single match often opens at twelve to fifteen per cent and pushes higher once the legs are correlated. The reader who knows where the margin lives can choose the layer that suits a stake size — a small punter chasing in-play action pays more for the privilege; a disciplined punter staking singles on the match winner pays less.
How the margin shows up in the numbers
A market with a real 50/50 line — two evenly priced opponents — is a useful example. Take a theoretical match priced at decimal odds 1.90 / 1.90 (9/10 each). To find what the bookmaker keeps of every pound staked, sum the implied probabilities the two prices imply: 1 ÷ 1.90 = 0.5263 for each outcome, giving 1.0526 in total. That sum is the overround — 105.26 per cent of a perfectly priced market, or a bookmaker’s edge of about 5.3 per cent, depending on rounding. The narrower the price (closer to evens at 2.00), the smaller the implied edge; the wider the price on a heavy favourite, the larger the per-pound hold on that side, because the favourite carries the heavier implied probability and the same percentage edge produces a bigger absolute take.
The honest result, with the rounding research gives, is a margin of roughly five per cent on a balanced two-way line at 1.90 — the band a punter should expect on most table tennis match-winner markets before promotions are applied, and the floor a punter should accept on a heavily favoured favourite. Anything comfortably wider than that on a one-off price is worth questioning: either the line has moved with late information, or the bookmaker is taking more than the market norm for liquidity reasons. The reader who can spot a five-per-cent margin at a glance stops seeing prices as numbers and starts seeing them as fees.
Reading a price without copying it
A bookmaker’s job is to balance the book, not to publish the true probability of each outcome. The reader’s job is the opposite — to estimate the true probability and to ask whether the price on offer exceeds it once the margin is stripped out. A price of 1.91 (about 10/11) on a match the punter rates at 55 per cent is a value bet, because the fair price at 55 per cent would be 1.82 (1 ÷ 0.55) and the offer sits above that. A price of 1.65 (about 13/20) on a match the punter rates at 65 per cent is the same answer by a different route. The point is not the size of the price but the gap between the price and the punter’s own estimate of probability.
No punter gets that estimate right every time, and no margin is uniform across markets. A punter who prices twenty matches a week at five per cent edge in the margin and finds genuine value on a third of them is doing well; a punter who prices five matches at the same edge and finds value on none is paying the bookmaker for the privilege of losing more slowly. That is the arithmetic under every table tennis coupon and it is the same arithmetic whether the sport is tennis, football or handball — table tennis simply gives a punter more fixtures to work through, which is both an opportunity and a discipline problem.
Same-game multiples and the cost of correlation
A bet builder stitches several legs on one match into one price, and the stitch is not free. Each leg carries its own margin; the builder stacks those margins on top of each other, and then compounds the result with a correlation adjustment — because two outcomes on the same match are not independent (a player winning the first game makes it likelier that they will win the second, which makes a handicap line more correlated to a total-points line than the legs would be on different matches). The result, on a three-leg same-game builder on a balanced match, is a margin typically in the range of twelve to eighteen per cent depending on the legs chosen and the bookmaker’s pricing model. The punter who reaches for the builder for the convenience of one stake on one match is paying two to three times the margin of a single on the match winner, and the builder should be reserved for the rare occasions when the correlation genuinely favours the punter’s view.
A related construction is the accumulator across several matches. Each leg carries its own margin and the legs multiply into one price, but here the legs are genuinely independent and the correlation is zero. A four-leg acca across four different matches, each at 1.80 decimal (4/5), compounds to about 10.5 in decimal odds — a return of £10.50 on a £1 stake — with a margin that is roughly the average leg margin compounded rather than stacked, because there is no correlation adjustment between matches. The acca is the cheapest way to combine several singles into one stake; the builder is the most expensive.
Spread betting and the FCA’s separate perimeter
Spread betting on a sporting index is a different product from fixed-odds betting and lives under a separate regulator. Spreadex, one of the brands below, is regulated by the Financial Conduct Authority for financial spread betting and by the Gambling Commission for fixed-odds betting — and the firm’s own terms state that losses on a sporting spread can exceed the original deposit, because the buyer of the spread is leveraged on every point of movement in the index. A punter who is used to fixed-odds stakes has to reset their thinking: a £1 stake per point on a total-points spread of 35–37 means a £10 loss for every point below 35 and a £10 gain for every point above 37, and a player retiring at 0–2 in the third game can wipe the deposit several times over.
The distinction is worth carrying forward. Fixed-odds betting on a table tennis match is the Commission-regulated product the rest of this guide describes; spread betting on a table tennis index is the FCA-regulated leveraged product with its own risk profile. The two are sold by the same firms in some cases, and a punter who picks up a spread product by accident has not picked up a fixed-odds bet with a wider margin — they have picked up a leveraged position with a different loss profile.
The sport and its tournaments
Where the fixtures come from
Table tennis is one of the deeper fixture lists in British bookmakers’ in-play feeds. The ITTF was founded in 1926 and the sport has been on the Olympic programme since 1988, and across that history a global calendar has built up around a small number of anchor events. The Olympic tournament and the World Championships sit at the apex; the ITTF World Tour and its successor, the WTT (World Table Tennis) series, fill the year with regular events at Grand Smash, WTT Champions, WTT Star Contender and WTT Contender levels; the continental championships — European, Asian, Pan-American — sit between the world events and the national leagues; and a thick tail of national leagues, Challenger events and Pro Tours rounds out the calendar. The WTT series in particular now runs almost continuously across Asia, Europe and the Americas, with enough weekly fixtures that a British bookmaker’s table tennis page rarely sits empty.
That depth is the reason the market is here. Football and horse racing have their peaks; table tennis has a steady tide. A punter who logs in on a Tuesday afternoon in March is likely to find a WTT Contender event live somewhere with markets open; a punter who logs in on a Sunday morning in November is likely to find a European national league tie. The calendar does not stop, and that changes how a punter plans their week — there is always another match to price, which is a feature if it disciplines a punter’s stake size and a bug if it tempts a punter into too many bets.
What the fixture list means for the punter’s research
Depth of fixture brings depth of information and depth of trap. The information side is real — the ITTF publishes world rankings, the WTT publishes head-to-head records, and the leading players publish enough recent results that a punter can build a model of form over the last six to twelve months. The trap is that table tennis is volatile — a young player can rise fast on the back of one good tournament, a veteran can fall quickly after a loss of form, and the difference between a top-20 player on a confident run and a top-20 player off form is wide enough to overturn the head-to-head market. The punter who works from rankings alone is paying for a lagging indicator; the punter who works from form alone is paying for a noisy one. The middle path — a rolling window of the last six months’ results against comparable opponents, weighted for surface and tournament level — is the discipline the sport rewards.
A second discipline is the surface and the ball. Modern table tennis is played on a small number of standardised surfaces, but the speed of the ball (the plastic ball introduced by the ITTF in 2014 replaced the older celluloid ball) and the indoor conditions — humidity, altitude, the lighting in a particular arena — change the way the ball travels and the kind of player who thrives. A European-based event is more often a slower-surface game that rewards defenders and spinners; an Asian-based event on a faster surface rewards flat hitters and aggressive servers. The punter who treats every WTT Contender as one homogeneous event is paying for ignoring context.
Head-to-heads and the trap of small samples
The market that tempts most punters into the worst bets is the head-to-head. Two players may have met five times in their careers, and three of those meetings may have gone one way — a record that looks decisive until the punter looks at the conditions. Two of those three wins may have come on a slow European surface against a defender who has since changed rubber; one may have come in a low-ranked Challenger event with both players fatigued from travel. Five meetings is not a sample; ten meetings is a thin sample; twenty meetings across at least two seasons and several surfaces is the floor at which a head-to-head becomes a useful input rather than a misleading one. The punter who backs a player on the strength of three wins in five meetings without checking what those matches were is paying for a small-sample illusion.
The same caution applies to live in-play markets, where the punter is watching the match unfold and the temptation is to bet on the next game based on momentum. Momentum in table tennis is real — a player who has just won a tight game carries confidence and the opponent carries doubt — but a single service break in a game can swing the price several ticks before the punter has time to react, and the bookmaker’s margin on the next-game market is wider than on the match-winner market because the model is less refined. The punter who reads momentum well is paying a high margin for the privilege; the punter who reads momentum badly is paying a high margin for a faster loss.
Ten UK bookmakers for table tennis: the comparison
How the shortlist was built
The ten brands below all hold a remote general betting standard (real events) licence from the Gambling Commission and are listed on the Commission’s public register. That is the only criterion for inclusion: every GB-licensed online betting operator must take part in GAMSTOP, must verify the customer’s age and identity before the first deposit, and is subject to the Commission’s marketing and social responsibility codes. A place on this shortlist is not a recommendation — it is the floor. Above that floor, each brand offers a slightly different package: a stronger in-play product here, a longer racing pedigree there, a leaner mobile app elsewhere, and a free-bet welcome offer (described only in qualitative terms below; no working code is printed) at most. The verdict on each block names what the brand is genuinely good at, not whether it is universally good.
The brands below are ordered by the order they appear on the Commission’s register for this comparison, not by any measure of quality. The reader who wants a brand for in-play depth should read the blocks; the reader who wants a brand for a free-bet welcome offer should read the blocks; the reader who wants the cheapest margin on the match-winner market should test several of them on the same match before staking. The table below summarises the licensing detail and the table-tennis-relevant terms each brand publishes; the sections beneath it close each brand on its own merit.
| Brand | Gambling Commission remote licence | Licence holder | What the operator’s terms say about table tennis |
|---|---|---|---|
| Copybet | Account 53774 (licence 053774-R-330743-010) | Copybet UK Limited | Best Odds Guaranteed all day, every day, on UK and Irish racing; first-past-the-post payouts on horse racing apply even if the winner is later disqualified. |
| Bet600 | Account 44731 (licence 044731-R-323941-016) | Tyche Tech Limited | Best Odds Guaranteed on horse racing: bets at the early or show price are paid at the larger starting price where the SP is bigger. |
| Betfair | Account 39439 (licence 039439-R-319330-013) | PPB Counterparty Services Limited | In-play betting, Bet Builder, free live streaming within the app (UK and Irish racing and football among them) and a 90 Minute Payout market. |
| London Bet | Account 66162 (licence 066162-R-340278-004) | Thistle Bet Limited | Sports betting (football, tennis, horse racing, greyhounds, darts, golf, cricket, NFL, NBA, MLB, snooker) with Pragmatic Play casino slots and live in-play markets. |
| 888sport | Account 39028 (licence 039028-R-319297-014) | 888 UK Limited | Pre-match and in-play betting, Cash Out, Bet Builder, racing streams, BetFinder form tools, a live bet feed and daily boosted odds. |
| Bet Ahoy | Account 100094 (licence 100094-R-341742-003) | Bet Ahoy Ltd | 10% Acca Bonus up to £1,000, Sub-Cover for player substitutions, Best Odds Guaranteed on UK and Irish horse and greyhound racing up to £100, and Double Result payout on UK and Irish racing. |
| Fitzdares | Account 400 (licence 000400-R-103839-030) | Fitzdares Limited | Cash out, accumulators, Lucky 15s, specials and antepost markets across horse racing, football, tennis, rugby, cricket, golf and American football, with in-play live odds. |
| BetVictor | Account 39576 (licence 039576-R-319370-028) | BV Gaming Limited | Best Odds Guaranteed on UK and Irish horse racing, enhanced live race streaming and a BetFinder feature, with Smart Stats alongside. |
| NetBet | Account 39170 (licence 039170-R-319343-032) | Netbet Enterprises Limited | Daily Boosts, Profit Boosts and free bet offers, a Bet Builder with instant dynamic odds, and sports stats for the major leagues. |
| Spreadex | Account 8835 (licence 008835-R-104580-022) | Spreadex Limited | £60 in free bets for a £10 fixed-odds qualifying bet for new customers; free bets usable across fixed odds and spread betting; qualifying bet must be placed within 28 days of opening the account. |
The Commission requires name, address and date of birth to be verified before a customer can deposit or gamble with any of these brands, and credit cards have been banned for gambling in Great Britain since 14 April 2020 — including credit-card-funded payments through an e-wallet. Every brand on the list is a GAMSTOP member, so a punter who has self-excluded through GAMSTOP is blocked at sign-up rather than at deposit. The reader who wants to confirm a licence — including for a brand not on this shortlist — can search the Commission’s public register by business name, trading name, domain or account number.
Copybet
Copybet holds Commission Account 53774 and runs on its Best Odds Guaranteed offer, which is unusually broad: all day, every day, on UK and Irish racing. Most brands apply BOG only on certain race types or after a certain hour; Copybet applies it from the moment the price is taken. The brand also pays first past the post on horse racing even when the winner is later disqualified, which protects a punter from the steward-after-the-flag sting. For a punter whose interest in the bookmaker is horse racing rather than table tennis, that is the headline feature. For a table tennis punter, the proposition is more ordinary — a licensed GB bookmaker with standard markets and standard in-play coverage, run by Copybet UK Limited.
The verdict: a brand worth considering for the racing punter who values its specific BOG terms, and an ordinary licensed bookmaker for the table tennis punter who wants a place in a rotation. The welcome offer exists in qualitative terms only and the reader should check Copybet’s own terms page for the current wording.
Bet600
Bet600 is held under Tyche Tech Limited and runs the same BOG model as Copybet — bets at the early or show price are paid at the starting price if the SP is bigger — though the racing coverage and the table tennis market in CoBeta are narrower than Copybet’s. The brand is younger than most on this list and the mobile experience is the centre of the proposition, which matters less for a punter working from a desktop and matters more for a punter staking from a phone at a WTT Contender event. Table tennis is on the coupon in the standard match-winner, handicap and totals shape; the in-play coverage is real-time but not deep, and a punter looking for next-point or race-to-X markets will find fewer of them here than at Betfair or 888sport.
The verdict: a brand for the punter who wants a licensed GB bookmaker with a clean mobile interface and standard racing terms, and who does not need the deepest in-play book on table tennis. Not the right pick for a punter building a same-game multiple on a fifth set.
Betfair
Betfair sits on Commission Account 39354 and is run by PPB Counterparty Services Limited — the same group that runs Paddy Power, which is why two of the largest betting brands in Britain share one licence. The Sportsbook product is separate from the Exchange: the Exchange runs under a betting intermediary licence and offers back and lay prices set by other customers; the Sportsbook offers fixed-odds markets set by the firm. For a table tennis punter, the relevant proposition is the Sportsbook plus the Exchange, which together give a depth of price and a depth of market type that the rest of this shortlist does not match. The firm offers in-play betting, a Bet Builder, free live streaming inside the app for events including UK and Irish horse racing and football, and a 90 Minute Payout market on football that pays out if the backed team goes two goals up regardless of the final result.
For table tennis specifically, the Sportsbook carries the full range — match winner, handicap, totals, in-play next-game markets — and the Exchange carries the same plus lay bets, which a punter can use to trade out of a position mid-match. The depth of liquidity on the Exchange varies with the tournament; WTT Smashes and World Championships are liquid enough that a punter can place a lay bet at a reasonable size; Challenger events may be too thin for a meaningful lay.
The verdict: the strongest table tennis proposition on this shortlist, because it offers both a Sportsbook and an Exchange and because the in-play feed is one of the deepest. The welcome offer exists in qualitative terms only and the reader should check Betfair’s own terms for the current wording. For a punter who wants to back and lay on the same match, the Exchange is the answer.
London Bet
London Bet is published by London Bet Limited, holds Commission Account 66162, and combines a sportsbook with Pragmatic Play casino slots inside one app. The sports coverage is wider than the brand name suggests — football, tennis, horse racing, greyhounds, darts, golf, cricket, NFL, NBA, MLB and snooker — and live in-play markets sit alongside the casino lobby. The proposition is more of a one-app hybrid than a specialist sportsbook, and a punter whose primary interest is a deep table tennis in-play feed will find fewer markets here than at Betfair or 888sport. What the brand offers is the convenience of a casino-and-sports app in one place, with a 17+ App Store age rating on the iOS listing.
The verdict: a brand for the punter who wants a single licensed GB app for both sports and slots, and who does not need a specialist table tennis in-play product. Any welcome offer is subject to the brand’s current terms, which the reader should verify before staking.
888sport
888sport is held under 888 UK Limited on Commission Account 39028 and offers pre-match and in-play betting, Cash Out, Bet Builder, racing streams, a BetFinder form tool, a live bet feed and daily boosted odds across the major sports. For a punter who likes the builder structure on football, the same product sits on tennis and table tennis; the live bet feed gives the punter a quick visual of what other customers are backing, which is useful for sniffing out the market’s drift on a match the punter has priced themselves. The Cash Out function is standard — settle the bet before the final outcome at a price the firm sets — and the punter should expect a Cash Out margin that is wider than the pre-match margin, because the firm is pricing a one-sided position.
The verdict: a brand for the punter who likes Cash Out, Bet Builder and the social signal of a live bet feed, with a strong general sportsbook proposition and a standard table tennis offering. The welcome offer exists in qualitative terms only and the reader should check 888sport’s own terms for the current wording.
Bet Ahoy
Bet Ahoy is held under Bet Ahoy Ltd on Commission Account 100094 and is one of the more aggressive new entrants on the GB register. The headline terms are a 10% Acca Bonus up to £1,000 — extra winnings on a winning accumulator — and Sub-Cover, which refunds stakes on player-substitution markets when a named player is taken off before the relevant event. The brand also offers Best Odds Guaranteed on UK and Irish horse and greyhound racing up to £100 and a Double Result payout on UK and Irish racing. For a punter who builds accumulators across several matches, the 10% bonus is real money on top of the win; for a punter who backs singles, the proposition is the rest of the coupon. Table tennis markets are present in standard form and the brand’s mobile app is the centre of the offering.
The welcome offer structure is the most distinctive thing about Bet Ahoy — a meaningful acca bonus is rarer than a fixed-odds free bet — and a punter whose staking pattern is acca-heavy will look at this brand harder than a punter whose staking pattern is single-heavy.
The verdict: a brand for the punter who builds accumulators and wants the acca bonus on top of the win, with standard table tennis markets and a young mobile-first product. The terms for the welcome structure are at the operator’s site, and we recommend checking them in full before committing a first deposit.
Fitzdares
Fitzdares is held under Fitzdares Limited on Commission Account 400 — one of the oldest account numbers on the GB register, predating most of the brands on this list by years. The proposition is a premium sportsbook with cash out, accumulators, Lucky 15s, specials and antepost markets across horse racing, football, tennis, rugby, cricket, golf and American football, with in-play live odds. The brand trades on its racing pedigree and its high-end customer service, which is the kind of thing that matters to a high-staking punter and matters less to a casual one. Table tennis is on the coupon; the depth is standard rather than specialist.
The verdict: a brand for the high-staking punter who values the racing pedigree and the personal-service angle, and who does not need a specialist table tennis in-play book. Readers should verify the specifics of any welcome promotion on the operator’s official terms page.
BetVictor
BetVictor is held under BV Gaming Limited on Commission Account 39576 — one of the longer-established online brands in Britain, with a heritage that runs back to the Victor Chandler era. The current proposition includes Best Odds Guaranteed on UK and Irish horse racing, enhanced live race streaming and a BetFinder feature for finding racing bets, with Smart Stats sitting alongside as a research tool. The racing proposition is the centre of the brand; the sportsbook carries football, tennis and the rest in standard form. Table tennis is on the coupon; the in-play product is competent rather than best-in-class, and a punter whose interest is the football builder will find the same builder here as elsewhere.
The verdict: a brand for the punter who values the racing proposition and the Smart Stats research tools, and who wants a long-established licensed GB bookmaker in the rotation. The brand’s site lists the terms for any available promotion, which the reader should review independently.
NetBet
NetBet is held under Netbet Enterprises Limited on Commission Account 39170 and runs a Daily Boosts and Profit Boosts model, with a Bet Builder that updates its odds in real time as the punter adds legs, and sports stats for the major leagues. The boost structure is the centre of the brand: a Daily Boost is a one-off enhanced price on a chosen selection; a Profit Boost is a token the punter uses to mark up the price on a chosen accumulator. For a punter who likes to chase boosted prices, the daily cadence gives a regular thread to pull on. Table tennis is on the coupon; the depth is standard.
The verdict: a brand for the punter who likes daily boosted prices and a real-time builder, with a standard table tennis offering and a clear mobile app. Current terms for any bonus are maintained at the brand’s own site, and verifying them is the best way to understand the offer.
Spreadex
Spreadex is held under Spreadex Limited on Commission Account 8835 and is the only brand on this shortlist that combines fixed-odds betting with FCA-regulated financial spread betting on the same app. The firm’s own terms are unusually explicit about the risk of the spread product — losses on a sporting spread can exceed the original deposit, because the buyer is leveraged on every point of movement in the index. For a punter who understands that profile, the spread product is a useful addition to a fixed-odds book; for a punter who does not, the fixed-odds product is the only part to use, and the spread product should be left alone. The brand’s welcome offer for new customers is £60 in free bets for a £10 fixed-odds qualifying bet, with the free bets usable across fixed odds and spread betting and the qualifying bet to be placed within 28 days of opening the account. Free bets of that scale are described only in the qualitative terms the brand itself publishes — the wagering requirement, the minimum odds on the qualifying bet, the expiry on the free bets themselves, are all on the brand’s own current terms.
The verdict: a brand for the punter who understands the difference between fixed-odds and spread betting and who wants both in one app, and a brand to be careful with for the punter who does not. For table tennis specifically, the fixed-odds proposition is standard; the spread product on a sporting index is a separate beast with its own risk profile.
Fundamentals: how a punter builds a price from nothing
Form, statistics and the bookmaker’s own odds
A price is built from three inputs: the punter’s own estimate of probability, the market’s implied probability (read from the bookmaker’s odds), and the gap between them. The first input is the hard one. Form over the last six to twelve months gives a sense of where the player’s level is; head-to-head records against comparable opponents sharpen the estimate for a specific match-up; surface and tournament level provide the context for both. The market’s implied probability is read directly from the bookmaker’s decimal odds — a price of 1.91 implies 52.4 per cent, a price of 3.50 implies 28.6 per cent, a price of 6.00 implies 16.7 per cent. The gap between the two is the value, and the gap has to clear the bookmaker’s margin before the bet is a value bet.
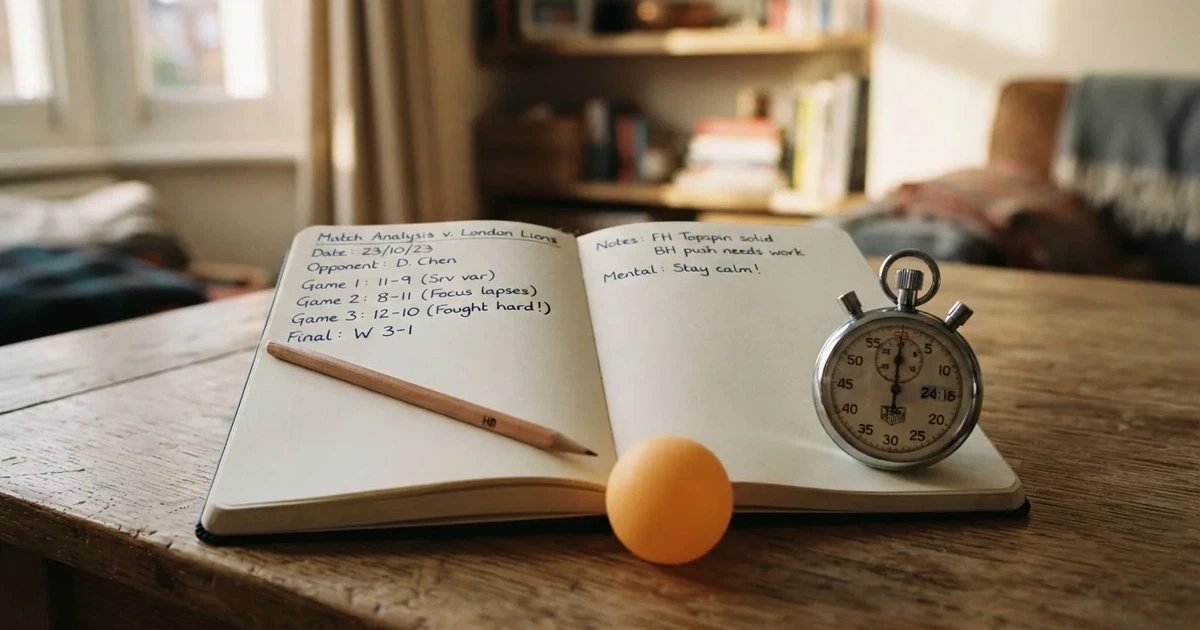
The discipline that makes the discipline work is honesty about probability. A punter who estimates a player at 60 per cent to win when the form and the head-to-head support 55 per cent is overstating their edge and will lose on the bets where the market is roughly right. A punter who estimates the player at 50 per cent when the form supports 55 is understating their edge and will miss value bets. The middle path — a record of probabilities that comes out roughly right over a hundred matches — is the path the punter should be working toward, and keeping a consistent log is the essential step for validating that progress.
Bankroll discipline and the cost of variance
A punter with a five per cent edge over the market on a defined subset of bets is still going to lose more often than they win, because the variance of binary outcomes is high and a 55/45 proposition loses 45 per cent of the time. The discipline is to stake the same fraction of the bank on each bet — a unit of one to two per cent of the bank is the conventional starting point — so that a run of twenty losing bets in a row wipes only twenty to forty per cent of the bank rather than the whole of it, and so that the winning bets come back at a size that recovers the losses and grows the bank.
The arithmetic is worth saying in plain numbers. A punter with a £1,000 bank staking £20 a bet at a 55 per cent win rate and average decimal odds of 1.85 makes a profit of about £0.70 per bet on average — a £10.40 return on a £20 stake against a £9.30 average loss, summed across 100 bets, gives roughly £70 of profit before the bookmaker’s margin is counted. The same punter at a 45 per cent win rate and the same odds loses about £11.30 per bet. The difference between the two is the punter’s edge; the difference is not the stake size. Chasing losses by raising the stake is the path that breaks bankrolls, not the path that fixes them.
Why no tip is ever certain
A tip is a probability estimate stated as a recommendation. The probability can be 60 per cent and the recommendation can still lose — a 40 per cent proposition loses four times in ten on average, which is most of the time. The reader who treats a tip as a certainty is wrong on the definition; the reader who treats a tip as a probability estimate is right on the definition and has to ask what probability the tip represents before staking on it. The honest tipster publishes a record — the number of bets, the strike rate, the average odds, the closing bank — and the reader judges the record rather than the latest pick. The dishonest tipster publishes a pick without a record, and the reader who backs it on unknown data is paying for someone else’s guess.
The market amplifies the point. A tip from a paid service that lands 55 per cent of the time at average decimal odds of 1.90 makes about £0.45 per £1 staked on average — a small edge, eroded by the bookmaker’s margin and the variance of the sample. The same tip copied across a hundred followers pays the same edge on the same bets, with the bookmaker pocketing a margin on each copy. The punter who reads a tip and asks what the probability is, what the edge is, and what the variance is over a year is doing the work; the punter who reads a tip and stakes on it is paying for the tipster’s record without doing it.
Statute and jurisdiction: how the GB licence frames the market
The Gambling Commission and the Act
The Gambling Commission is a non-departmental public body sponsored by the Department for Culture, Media and Sport, and it licenses the whole commercial market in Great Britain under the Gambling Act 2005. The Act covers England, Scotland and Wales; Northern Ireland sits outside the Act and runs its own older law, so a “GB-licensed” bookmaker is licensed for customers in Great Britain rather than the United Kingdom as a whole. Since the Gambling (Licensing and Advertising) Act 2014, an operator whose remote facilities are used in Great Britain needs a Commission licence wherever it is based — sections 33 and 36 of the 2005 Act as amended — and a Curaçao, Maltese or Gibraltar licence is not a substitute. There is no state monopoly and no cap on the number of licences; the Commission issues licences to applicants who pass the tests in the Act and the Licence Conditions and Codes of Practice (LCCP).
The Commission’s public register can be searched by business name, trading name, domain or account number, and is the whole test of whether a brand holds a licence. The reader who wants to check any brand — including one named on this page — should search the register rather than the marketing, because licensed operators use .com as well as .co.uk and the domain proves nothing on its own.
Betting licence categories
The Commission issues betting licences under several categories. Remote general betting standard (real events) is the category every brand on this shortlist holds — it covers fixed-odds and pool betting on real sporting fixtures, the bread and butter of the GB sportsbook. Remote general betting standard (virtual events) is a separate category covering computer-generated events. Remote pool betting covers pool betting on horse and dog racing. Remote betting intermediary is the licence for betting exchanges. Remote general betting limited is a smaller-scale category with turnover caps. A brand may hold one or several of these, and the category it holds governs what markets it can lawfully offer. The brands on this shortlist hold remote general betting standard (real events) and offer table tennis under that category.
Spread betting on financial markets is regulated by the Financial Conduct Authority, not the Commission — and Spreadex, which offers both fixed-odds sports betting and FCA-regulated spread betting, holds the two licences separately. The reader who picks up a spread product from Spreadex has picked up an FCA-regulated product with its own risk profile, not a fixed-odds bet with a wider margin.
Identity verification, age and credit cards
Three rules apply at the door of every licensed brand. The minimum age is 18; name, address and date of birth are verified before the customer can deposit or gamble (in force since 7 May 2019), including with a free bet or bonus; credit cards have been banned for gambling in Great Britain since 14 April 2020 (LCCP condition 6.1.2), including credit-card-funded payments through an e-wallet. The reader who wants to deposit anonymously at a licensed brand cannot, and the reader who wants to use a credit card cannot — both rules are at the licence level, not the brand level, and there is no licensed route around them.
The identity check is the moment a punter’s account moves from a registration to a verified account, and the time it takes varies by brand and by the documents the customer supplies. A punter who wants to bet on a table tennis match in fifteen minutes should open the account and verify earlier in the day; a punter who bets on a weekend WTT Smash should verify on the Friday before.
Player protection: GAMSTOP, deposit limits and the vulnerability check
GAMSTOP is the national multi-operator online self-exclusion scheme, and a mandatory licence condition for every GB-licensed online operator since 31 March 2020. Self-exclusion periods are six months, one year, five years, or five years with auto-renewal; after the minimum period has elapsed, the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps; betting shops use a separate service. A punter who has self-excluded through GAMSTOP is blocked at sign-up at every brand on this shortlist.
Deposit limits (RTS 12) require operators to offer a gross deposit limit on a fixed time frame. The first changes applied from 31 October 2025; a second phase was postponed to 30 September 2026, and whether it is live is not established. The deposit limit is the customer’s choice; there is no state-set deposit or loss ceiling for betting.
A financial vulnerability check (LCCP condition 3.4.4, in force since 30 August 2024) applies to licensed remote betting when a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days (since 28 February 2025). The check is a public-record check — for example bankruptcy or county court judgments — not an income check and not a credit reference check. Financial risk assessments (the “affordability checks” of the press) are announced in a staged plan (Commission article of 7 July 2026) with no start date. The reader who wants to know what stage is live should check the Commission’s own announcements rather than the press.
Bonus marketing rules
Wagering requirements on bonuses are capped at 10x as of 19 January 2026 — a £10 bonus at 50x needed £500 of bets before the new rule; under the cap no more than £100. Mixed-product promotions — an offer that requires gambling on two or more product types, for example “bet on football to get free spins” — are banned. The reader who wants to claim any of the welcome offers named on this page should check the brand’s own current terms for the wagering requirement, the minimum odds on the qualifying bet, and the expiry of the free bet before staking.
The welcome offers on this shortlist are described in qualitative terms only — the kind of welcome offer, the order of magnitude of the free bet, the markets it applies to — and no working code is printed. The reader who wants to claim a specific welcome offer should check the brand’s own current terms; the reader who wants to compare available offers should use the descriptions on this page as a starting point and confirm the current details at the operator’s own site.
Tax, advertising and the offshore question
The player pays no tax on betting winnings in Great Britain — that is general information, not tax advice, and a professional gambler should ask HMRC or an adviser. General Betting Duty is the operator’s tax on gross profits, currently 15%; from 1 April 2027 a remote betting rate of 25% applies within it, while remote bets on UK horse racing, bets on self-service betting terminals in licensed premises, pool betting and in-person betting stay at 15%. Until 1 April 2027 the remote rate stays at 15%; whether operators pass the duty on through odds is not established, and the reader should not assume the player is charged duty directly.
Advertising is not licensed by the Commission; it runs through the CAP Code (non-broadcast) and BCAP Code (broadcast), enforced by the ASA, alongside the LCCP marketing conditions. CAP Code section 16 says marketing must be socially responsible, must not be of strong appeal to under-18s, and no one who is or seems to be under 25 may be featured gambling or play a significant role (with an exception for marketing placed where a bet can be made directly). That rule concerns who may appear in an advertisement, not who may bet. The “whistle-to-whistle” rule — no betting advertising on TV from five minutes before a live sporting event to five minutes after, before the 9pm watershed — is an industry code, not law, in force since 1 August 2019; horse and greyhound racing are excluded.
A GB licence is compulsory at the point of consumption. Providing gambling facilities in Great Britain without the licence the Act requires is an offence under section 33 of the Gambling Act 2005 — aimed at the operator, not the customer. A customer who bets on an unlicensed site does not commit an offence, but loses the GB-licensed protections: no GAMSTOP coverage, no Commission complaints route, no approved dispute-resolution body, no British consumer redress if funds are withheld, not bound by the 10x bonus cap or the £150 vulnerability check. Enforcement is disruption, not blocking: cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers; the Commission has been given, or is about to receive, court-order DNS blocking powers — never write that ISP blocking is in operation. The honest framing: licensed means checks, limits, GAMSTOP, the bonus cap, and identity verification before the first bet; unlicensed means none of those protections and possible loss of funds. Neither is “the safe choice” by default.
Responsible gambling: the support that sits around the bet
The Commission’s safer-gambling codes
The LCCP’s social responsibility code requires licensed operators to offer a range of safer-gambling tools — deposit limits, time-outs, product restrictions and self-exclusion — and to make them easy to find inside the app. A punter who wants to set a deposit limit at any brand on this shortlist can do so from the account settings, usually with effect from the next deposit. A punter who wants a longer break can self-exclude through the brand or through GAMSTOP, which extends the exclusion to every GB-licensed online operator at once. The Commission’s codes are not optional; a brand that fails the social responsibility code risks licence action, and the brands on this shortlist have all committed to the codes as a condition of holding the licence.
Unibet’s safer-gambling tools — set out on its UK homepage — are a useful example of what the codes look like in practice: deposit limits, a Player Profile test, product restrictions and self-exclusion, with live chat support and links to BeGambleAware, GamCare, GAMSTOP, Gambling Therapy and the BGC. Every brand on this shortlist carries the same set of tools in some form; the reader who wants to know what is offered by a specific brand should check that brand’s own safer-gambling page rather than this guide.
Where help is available outside the operator
GamCare runs the National Gambling Helpline and offers one-to-one support; GambleAware funds treatment and education; the NHS runs gambling clinics in several English regions; Gamblers Anonymous runs peer-support meetings across the country. The help is free, confidential and not tied to any single operator. A punter who is worried about their own betting — chasing losses, betting more than they can afford, hiding stakes from family — can call the National Gambling Helpline without giving a name and ask for a referral; a family member who is worried about someone else’s betting can do the same. The reader who wants to know what is available in their own region should check GamCare’s site or the NHS gambling clinic page for the local details.
The point of carrying these names forward is that the responsible-gambling frame is not the operator’s alone. GAMSTOP is at the licence level, but the help on the other side of GAMSTOP — the counselling, the treatment, the peer support — is run by independent bodies funded by the industry and the NHS. The reader who has self-excluded and wants support has somewhere to go beyond the operator’s own safer-gambling page.
The cost of the safer-gambling tools to the punter
The honest framing is that the safer-gambling tools cost a punter nothing to set and save them money the moment they bite. A deposit limit that stops a punter from chasing losses on a Wednesday night saves the bankroll that the punter would otherwise have spent. A GAMSTOP self-exclusion that runs for a year gives a punter twelve months in which to reconsider their betting, and seven further years during which the exclusion stays in place unless the punter asks GAMSTOP to remove it. The tools are not punitive — they are a customer’s choice between sticking with the bettor they planned to be and being the bettor the late-night stake would otherwise turn them into.
The Commission’s codes also require the operator to monitor for harm — patterns of deposits, chasing behaviour, late-night play — and to interact with the customer where the monitoring suggests harm. The interaction is not a punishment; it is a check-in, often a message in the app, sometimes a phone call. The punter who reads the interaction as intrusion is missing the point; the punter who reads it as the operator doing the licence-level work is reading it right.
Crypto and anonymity: what the GB licence leaves on the table
The named-account rule
Identity verification before the first deposit means no anonymous play at a licensed site. A punter who wants to bet on table tennis at any brand on this shortlist must supply name, address and date of birth, and must have those verified before a first stake. The verification is in force since 7 May 2019, and it applies to free bets and bonuses as well as cash deposits — the operator cannot let a punter claim a welcome offer without verifying the punter first. A punter who wants to bet anonymously has to leave the licensed market, and the unlicensed offshore market is a different proposition: no GAMSTOP coverage, no Commission complaints route, no approved dispute-resolution body, no British consumer redress if funds are withheld.
The named-account rule is also a source-of-funds question at higher spend. A punter whose deposits minus withdrawals exceed £150 in a rolling 30 days triggers a financial vulnerability check under LCCP condition 3.4.4 (in force since 30 August 2024, applied since 28 February 2025), and the check is a public-record search for markers like bankruptcy or county court judgments. A punter whose deposit pattern raises a money-laundering flag at a licensed brand can expect to be asked where the money came from, and the brand is obliged to do so under the money-laundering rules. The punter who is uncomfortable with the question can leave the brand; the brand is not in a position to leave the question.
Cryptocurrency at licensed brands
There is no established rule for or against cryptocurrency deposits at GB-licensed operators. A punter who wants to deposit in Bitcoin or stablecoin has to check each brand’s own payment-methods page; some brands accept crypto through a payment processor, some do not, and the licence-level position is not a blanket ban and not a blanket permission. The reader who wants to know whether a specific brand accepts crypto should check the brand’s own deposit page rather than this guide.
The point worth carrying forward is the asymmetry of protections. A licensed brand that accepts a crypto deposit still verifies the customer’s identity, still applies the GAMSTOP self-exclusion, still applies the £150 vulnerability check, and still operates under the Commission’s marketing and bonus rules. A punter who deposits in crypto at a licensed brand gets the GB-licensed protections; a punter who deposits in crypto at an unlicensed brand gets the protections of whichever jurisdiction the brand is licensed in — and those protections may not include any British consumer redress. The crypto part is the payment method, not the licence.
What anonymity costs the punter
Anonymity at an offshore brand costs the punter more than the loss of GAMSTOP coverage. A punter who bets at a brand licensed in Curaçao or Malta has no British complaints route if the brand withholds funds; has no recourse under British consumer law if the brand’s terms are unfair; has no British data-protection rights over the personal data the brand holds; and has no guarantee that the brand will pay out on a winning bet, because the brand’s own terms govern the dispute and the brand’s own regulator decides the outcome. The brand’s regulator may decide in the punter’s favour; the punter has no British mechanism to make that happen. The encrypted reading of the cost is that anonymity is a feature the customer buys by accepting a risk the licensed market does not carry.
The honest framing: a punter who values the GB-licensed protections — GAMSTOP, the £150 vulnerability check, the 10x bonus cap, the British complaints route, the source-of-funds check — gets those protections at the cost of anonymity and at the cost of identity verification before the first bet. A punter who values anonymity gets it at the cost of the GB-licensed protections. The choice is the punter’s; the trade-off is real.
Bonuses and free bets: what an offer is actually worth
How a free bet works
A free bet is a token the bookmaker credits to the customer’s account, which can be staked on a selection at the bookmaker’s odds. The stake is not usually returned with a winning free bet — a £10 free bet at decimal odds of 3.00 returns £20, not £30 — and the distinction matters. A punter who treats a £10 free bet as a £10 cash stake has miscounted; a punter who treats it as the right to keep the winnings from a £10 stake at the offered odds is reading it right. The size of the free bet is the punter’s stake; the return is the punter’s profit.
The fair value of a free bet depends on the odds the punter takes and the margin the bookmaker holds on the market. The arithmetic, in plain words: for a free bet whose stake is not returned, the value is the free-bet amount multiplied by the odds minus one, divided by the odds, multiplied by the payout share of the market. A £10 free bet at decimal odds of 4.00 on a market with a 95 per cent payout share is worth £10 × 3 ÷ 4 × 0.95 = £7.13 on average — the £10 is the punter’s stake, the £7.13 is what the punter should expect to walk away with across many such free bets. The free bet is worth more at higher odds and less at lower odds; the free bet is worth more on a low-margin market and less on a high-margin market. The probability with which the bet wins is folded into the payout share.
The honest result is that a free bet is worth less than its face value once the stake-not-returned rule and the bookmaker’s margin are counted. A £10 free bet at 4.00 on a 95 per cent payout share market is worth £7.13 on average, not £10. A £10 free bet at 1.80 on the same market is worth £10 × 0.80 ÷ 1.80 × 0.95 = £4.22 on average. The punter who treats a £10 free bet as £10 of value is overpaying by between £3 and £6 depending on the price, and the punter who treats it as the arithmetic above is reading the offer right.
How a bonus works
A bonus is a credit the bookmaker adds to the customer’s real-money balance, often in exchange for a deposit and a qualifying wager. The difference between a bonus and a free bet is that a bonus returns its stake — a £10 bonus staked at 3.00 returns £30, of which £10 is the bonus and £20 is the winnings — but the bonus comes with a wagering requirement: the punter has to bet the bonus amount (or the bonus plus deposit, depending on the offer) a number of times before the bonus and the winnings become withdrawable.
A wagering requirement of 10x on a £10 bonus means £100 of bets before withdrawal; a requirement of 5x on a £10 bonus plus a £10 deposit means £100 of bets before withdrawal. The 10x cap on bonuses in force since 19 January 2026 caps the worst end of the market, and the punter should refuse any bonus offer that asks for more. Bets at odds below the minimum — usually 1.50 or 2.00 decimal — do not count towards the requirement, and the punter who bets at odds below the minimum is paying for the bonus without ever progressing.
The cost of clearing a bonus is the expected turnover multiplied by the expected margin of the markets the punter bets on. A punter with a £100 turnover requirement at a 5 per cent margin on the markets they bet on is paying about £5 on average across the clearing period — the margin is the bookmaker’s edge on every pound staked, and £100 of bets at a 5 per cent margin is £5 of expected cost. A punter who clears the bonus with a single £100 bet at 1.80 is paying £5 on average; a punter who clears it across fifty £2 bets at 1.80 is paying the same £5 on average, because the total stake is the same. The cost does not depend on how the punter splits the stake; it depends on the total stake and the margin of the markets.
The plain conclusion: a bonus is worth its face value minus the expected cost of clearing it. A £10 bonus with a 10x wagering requirement at a 5 per cent market margin is worth £10 minus £5 = £5 on average, before the punter’s own time is counted. A punter who values their time at zero and the £5 of expected cost as a flat number may take the offer; a punter who values their time above zero should ask whether the offer is worth the effort. Mixed-product bonuses — bet on football to get free spins — are banned under the marketing rules in force since 19 January 2026, so a punter who sees one is being offered an unlicensed promotion and should refuse.
The “risk-free” wager that is not risk-free
A bookmaker’s “risk-free” bet is a refund of the stake if the bet loses, usually paid as a free bet rather than cash. The punter who backs a £10 “risk-free” bet at 3.00 and loses gets a £10 free bet back — the cash stake is gone. The arithmetic is the same as a regular free bet: the £10 free bet at the punter’s next odds is worth £10 × (odds − 1) ÷ odds × payout share on average, which is between £4 and £7 depending on the price. The punter who treats “risk-free” as a £10 refund in cash is reading the word; the punter who reads the term is reading the free bet.
The honest framing: a “risk-free” wager is a free bet conditional on a loss, and a free bet is worth less than its face value. The punter who claims the “risk-free” offer is paying nothing for the chance to win the first bet; the punter who loses the first bet is paying the bookmaker the difference between the £10 stake and the £4-to-£7 fair value of the £10 free bet. The offer is a real benefit to the punter who wins the first bet and a smaller benefit to the punter who loses it; the offer is not a refund in cash.
Live betting and cash out: how the in-play product frames the action
What in-play on table tennis looks like
In-play on table tennis is one of the deeper in-play feeds in the GB market. The match is short — most matches finish inside an hour and many finish inside thirty minutes — which means a punter who logs in for a WTT Contender event can watch a full match unfold with markets open throughout. The base in-play market is the match winner, which re-prices after every game; on top of that come next-point markets (next to score five, ten, fifteen), race-to-X markets (race to three in the current game), and totals markets (over/under a total-points line for the next game). The depth depends on the tournament: WTT Smashes and World Championships carry the full range; Challenger events carry match winner and game winner only.
The discipline that the in-play product rewards is the same discipline that the pre-match product rewards, applied faster. A punter who has priced a match at 60/40 pre-match has to ask whether the in-play price after a first-game win for the favourite is still value — the answer depends on the punter’s model of how the player reacts to going one and having lost rather than going one and having won. A punter who reads momentum well can find value in the post-game market; a punter who reads momentum badly pays the bookmaker’s wider margin on the in-play product for the privilege of losing more quickly.
Cash out and the price of closing a position early
Cash Out is the bookmaker’s offer to settle a bet before the final outcome, at a price the bookmaker sets. The Cash Out price is wider than the underlying market’s margin because the bookmaker is pricing a one-sided position — the bookmaker has to absorb the bet on the other side of the punter’s Cash Out, and the bookmaker charges for that absorption. A punter who Cashes Out a £10 back bet at decimal odds of 2.50 with a stake that would return £25 might be offered £18 to Cash Out — a £7 discount on the fair value of the bet, which is the bookmaker’s edge on the close.
The honest framing: Cash Out is a price the punter pays for the certainty of closing the position early, and the price is the bookmaker’s margin on the close. A punter who Cashes Out a winning bet is paying for the certainty; a punter who Cashes Out a losing bet is paying for the certainty of capping the loss, and the cap is the bookmaker’s offer rather than the punter’s choice. The punter who never Cashes Out pays no Cash Out margin; the punter who Cashes Out routinely should expect the cash-out margin to drag their overall returns below the pre-match margin on the same selections.
Streaming, scores and live data
Most brands on this shortlist carry live scores for table tennis matches as part of the in-play product, and some — Betfair and 888sport among them — carry live streaming inside the app for events including football and racing. The streaming coverage of table tennis is thinner than football or racing because the rights are not centralised the way Premier League or British horse racing rights are; a punter who wants to watch a match live is often relying on the bookmaker’s own scoreboard plus an external stream, and the punter who wants a single-screen experience has to check each brand’s coverage. The reader who wants to bet and watch on the same app should test Betfair and 888sport first; the reader who wants the deepest data should test the brand’s statistics product rather than its stream.
Predictions and strategy: the frame for picking a match
What a prediction actually is
A prediction is a probability estimate stated as a recommendation. The probability can be 60 per cent and the recommendation can still lose four times out of ten on average; the probability can be 70 per cent and the recommendation can still lose three times out of ten. The reader who treats a prediction as a certainty is wrong on the definition; the reader who treats it as a probability estimate is right on the definition and has to ask what probability the prediction represents before staking on it. The honest prediction publishes the probability alongside the pick; the dishonest prediction publishes the pick alone, and the punter who backs it is paying for someone else’s guess without the discipline of the probability.
The discipline of the prediction is the same discipline as the price. The punter who estimates a player’s chance at 60 per cent and the market implies 55 per cent has a five-point value gap; the punter who estimates 70 per cent and the market implies 60 per cent has a ten-point value gap; both are value bets at different sizes, and the difference is the punter’s own edge rather than the recommendation’s truth. The prediction is the input to the bet; the value gap is the bet itself.
Building a price from the ingredients
A price is built from form, head-to-head, surface, tournament level and the bookmaker’s own odds. Form over the last six to twelve months gives a sense of where the player’s level is — a top-20 player on a ten-match winning streak is a different proposition from a top-20 player on a ten-match losing streak. Head-to-head against comparable opponents sharpens the estimate for the specific match-up — a player who has beaten the opponent twice on slow surfaces in the last twelve months is a different proposition from a player who has never beaten the opponent. Surface and tournament level provide the context for both — a Challenger event on a fast surface is a different proposition from a World Championships match on a slow surface, even for the same two players.
The bookmaker’s own odds are the final input and the one the punter judges their own price against. The punter’s price is the gap between the punter’s probability estimate and the market’s implied probability; the punter who finds a gap larger than the bookmaker’s margin has found a value bet, and the punter who finds no such gap has found a market at fair value. The discipline that makes the discipline work is honesty about probability, and ensuring a balanced view over time rather than one based on fleeting results is the true test of that honesty.
The bet builder trap
A bet builder is convenient and expensive. The convenience is a single stake on a single match covering several legs; the expense is a margin stacked on top of each leg’s margin and compounded by a correlation adjustment. A three-leg same-game builder on a balanced match opens at a margin typically in the range of twelve to eighteen per cent, which is two to three times the margin on the match-winner single. The punter who reaches for the builder for the convenience is paying two to three times the margin of a single on the match winner; the punter who builds a three-match accumulator across three different matches pays the same compounded margin across three independent events and saves the correlation adjustment.
The honest framing: the bet builder is for the punter who has priced each leg separately and found value on each, and who wants to combine those value bets into one stake. The bet builder is not for the punter who has not priced the legs and is using the convenience of the builder as a substitute for the work. The punter who uses the builder as a substitute is paying a high margin for the privilege of guessing; the punter who uses the builder as a combination of priced legs is paying the same margin for the convenience of one stake.
Closing the loop
A punter who keeps a record — the date, the match, the price taken, the result, the closing bank — has the raw material to judge their own edge. A punter who does not keep a record has only the memory of the wins and the explanation for the losses, and the memory is always rosier than the record. The discipline of the record is the discipline that separates the punter who finds value from the punter who thinks they find value, and maintaining an honest account of every bet is the best way to tell which one you are.
Frequently asked questions about table tennis betting
How do you win at table tennis betting?
There is no winning system, because every match has two players and only one can win. A punter who bets on table tennis at a profit over a year does so by finding prices that exceed their own probability estimate after the bookmaker’s margin is taken out, by staking a consistent fraction of their bank on each bet, and by accepting that a 55/45 proposition loses 45 per cent of the time. The arithmetic is the discipline; the discipline is the work.
How do you place a table tennis bet?
Open an account with a Gambling Commission-licensed bookmaker, verify your identity, deposit by debit card or bank transfer, find the table tennis coupon, and add a selection to the bet slip. The minimum stake is set by the operator and is usually £0.05 or £0.10 on standard markets. The bet settles at the conclusion of the match, or earlier if you Cash Out, and the return is added to your withdrawable balance.
What is the difference between a single and an accumulator on table tennis?
A single is one bet on one selection; an accumulator is one bet on several selections, where all must win for the bet to pay out. The odds of an accumulator multiply into one price — three legs at 1.80 each compound to about 5.83 in decimal odds — and the margin of an accumulator is roughly the average leg margin compounded rather than stacked, because the legs are independent across different matches. A same-game bet builder is a different product: it carries a margin stacked on top of each leg’s margin and compounded by a correlation adjustment, and a three-leg builder on a balanced match typically opens at twelve to eighteen per cent margin.
What is a value bet and why is no tip ever certain?
A value bet is a price on offer that exceeds the punter’s own probability estimate once the bookmaker’s margin is taken out. A tip is a probability estimate stated as a recommendation, and a probability estimate can still be wrong — a 60 per cent proposition loses four times out of ten on average, which is most of the time. The tip is the input; the value gap is the bet; the certainty is never there.
What is the bookmaker’s margin and how can it be seen in the odds?
The margin is the bookmaker’s edge on a market, expressed as the percentage of every pound staked that the bookmaker keeps on average. It shows up in the odds as an overround — a sum of implied probabilities that exceeds 100 per cent. A balanced two-way market at decimal odds 1.90 / 1.90 carries an implied probability of 0.5263 per outcome, summing to 1.0526, which is a margin of roughly five per cent. The narrower the price, the smaller the implied edge; the wider the price on a heavy favourite, the larger the absolute take on that side.
How is the return on a bet worked out from the stake and the odds?
The return on a winning single is the stake multiplied by the decimal odds — a £10 stake at 2.50 returns £25, of which £10 is the stake returned and £15 is the profit. The return on a winning accumulator is the stake multiplied by the compounded odds of the legs — a £10 stake across three legs at 1.80 each returns about £58.30. The return on a free bet whose stake is not returned is the stake multiplied by the odds minus one — a £10 free bet at 3.00 returns £20, not £30. The formula does not change across single, accumulator or free bet; what changes is whether the stake is included in the return.
Tennis, darts & cue sports – Free bets
Content created by the «Free bets» team
